The Short Answer: Solar Incentives Can Sometimes Be Stacked
Solar incentives can sometimes be combined, but there is no universal stacking rule. A federal tax credit, state program, local incentive, utility payment, and battery benefit may each have different eligibility requirements, deadlines, funding limits, application procedures, and rules for how one benefit affects another.
As of the supplied research date, October 1, 2026, the federal Residential Clean Energy Credit under IRC §25D is unavailable for qualifying expenditures made after December 31, 2025. A payment or deposit made before that date did not preserve eligibility if the installation was completed afterward.
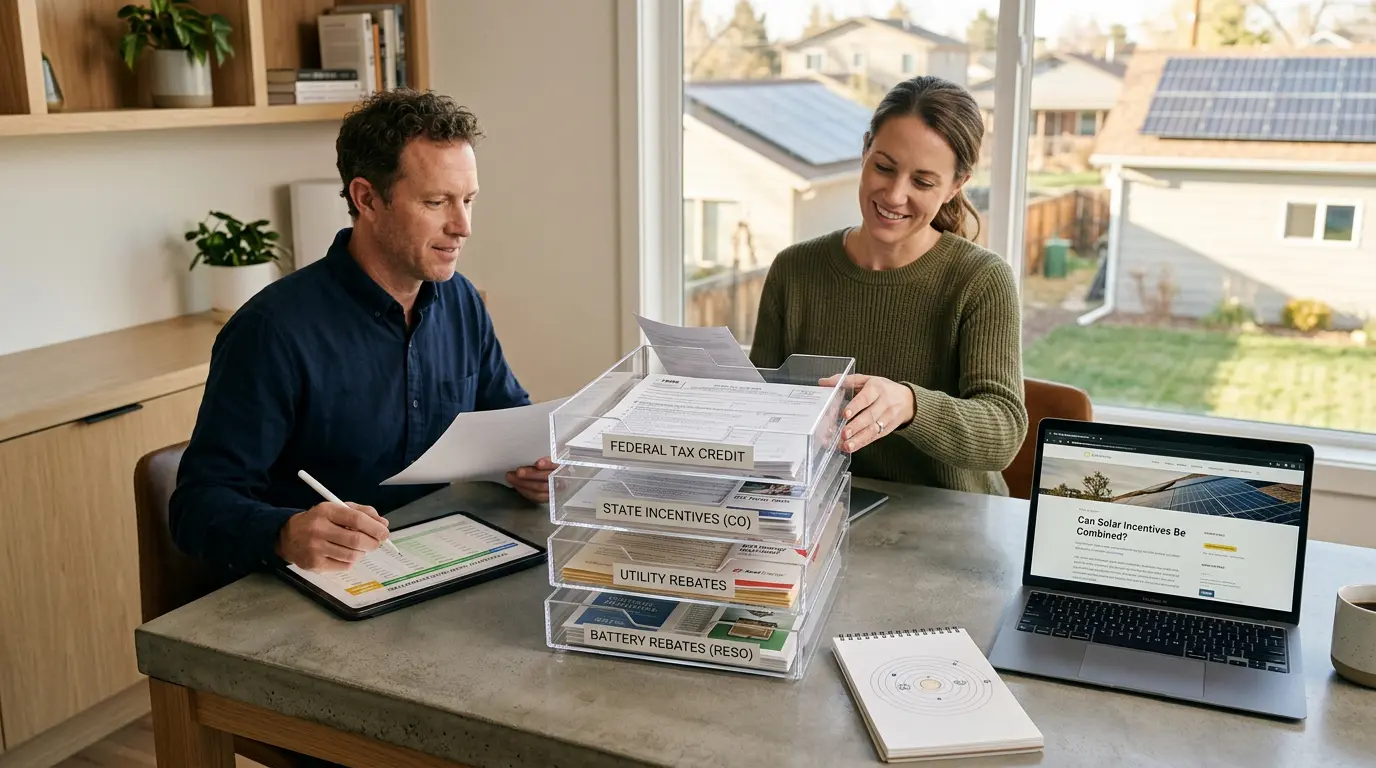
In practical terms, incentive stacking means using more than one benefit for the same project when the applicable program and tax rules permit it. The first step is to separate the benefits by type:
- Upfront rebates or purchase price reductions
- Federal or state tax credits
- Utility subsidies
- Bill credits and net metering
- Performance payments
- Loans and financing benefits
These benefits do not all reduce the same cost or operate under the same rules. A rebate and a tax credit may both apply, for example, but the rebate may reduce the cost used to calculate the tax credit.
The U.S. Department of Energy illustrates this concept with a $400 eligible purchase and a $100 rebate. The remaining $300 would be used as the basis for a 30 percent credit, producing a $90 credit. That is a program specific example involving IRA Home Energy Rebates and the §25C home improvement credit. It is not a universal calculation for every solar project or every §25D combination. The Department of Energy Home Energy Rebates requirements provide the example and its specific context.
Federal §25D Timing and Battery Rules
The former federal Residential Clean Energy Credit generally provided a 30 percent credit for qualifying residential solar electric property and qualifying battery storage expenditures made before the applicable deadline. As of October 1, 2026, that credit is not available for qualifying expenditures made after December 31, 2025.
The timing detail matters. Under the IRS FAQ, an expenditure is generally treated as made when original installation is completed. Paying a contractor, signing a contract, or making a deposit before December 31, 2025 did not preserve the credit if the installation was completed afterward. The IRS guidance on the §25D changes addresses this installation timing rule.
For eligible expenditures made before the deadline, qualifying battery storage generally had to meet a capacity threshold of at least 3 kWh. A battery was not automatically eligible merely because it was paired with solar panels. Ownership, residence, equipment, and installation requirements still mattered.
The former federal credit was nonrefundable. It could generally reduce federal tax liability to zero, but it could not create a refund beyond that liability. Unused amounts could generally be carried forward to a later year.
Those former federal rules should not be applied automatically to current state, local, utility, or battery programs. The end of §25D does not establish whether another incentive remains available. Each program must be reviewed on its own terms.
How Rebates, Utility Subsidies, and Net Metering Affect Cost Basis
The type of payment matters more than the label attached to it. A utility benefit described casually as a “solar incentive” could be a purchase subsidy, a rebate, a bill credit, a performance payment, or something else entirely. Those classifications can produce different tax treatment.
For the former §25D credit, public utility subsidies for purchasing or installing qualifying clean energy property generally reduced the qualified expense used to calculate the credit. This was true whether the payment went to the homeowner or directly to the contractor.
Net metering is different. Payments or credits for electricity sold back to the grid generally did not reduce qualified expenses for §25D. In other words, a bill credit tied to exported electricity was not treated the same way as a subsidy that helped pay for the solar equipment itself.
State incentives require separate analysis. A state program may use the word “rebate,” but that label alone does not determine whether the benefit is a rebate or purchase price adjustment for federal tax purposes. It may also have separate state tax consequences.
Before calculating combined savings, find out what each benefit actually is, who administers it, when it is paid, and whether it changes the eligible cost for another benefit. The IRS information on the Residential Clean Energy Credit explains the distinctions involving utility subsidies, net metering, and other incentives.
State, Local, Utility, and Battery Programs Require Location Specific Review
There is no standard nationwide package of state, local, utility, and battery incentives. Start with the property address, state, city or county, electric utility, and service territory. Those details determine which programs are even relevant.
Programs may differ in funding, effective dates, expiration dates, application windows, income limits, equipment requirements, contractor rules, preapproval requirements, and stacking provisions. Some may require an application before installation. Others may have limited funds or stop accepting applications when funding is exhausted.
DSIRE can help identify possible federal, state, local, and utility programs. Treat it as a discovery tool, not as final proof that a program is open, funded, or available to a particular homeowner. The administering authority’s current terms control.
Battery incentives deserve their own review. Do not assume that a solar rebate includes storage, or that a battery qualifies simply because it is installed at the same time as solar panels. Check the program’s equipment list, capacity rules, application timing, and stacking language.
Confirm Property, Ownership, Equipment, and Project Eligibility
Before comparing incentive amounts, document how the property is owned and used. Record whether it is an owner occupied primary residence, a second home, a rental, a cooperative, a condominium, or a mixed use property.
The former federal residential rules generally required the taxpayer to own the qualifying property and use the United States residence as a residence. An appropriate second home could qualify in some circumstances, while a landlord who did not reside in the dwelling generally could not claim the residential credit.
Used property did not qualify for the former residential credit. Equipment also had to meet the applicable program requirements. For a battery, that could include a capacity threshold or an approved equipment list. A homeowner’s title, residence, or equipment does not automatically satisfy every state, utility, or local program.
Rental, cooperative, condominium, and mixed business use situations can require fact specific review. The same project description may produce a different answer depending on who owns the equipment, who occupies the property, and which program is being claimed.
A Homeowner’s Incentive Stacking Checklist
Use a separate worksheet for every proposed benefit. Keeping everything in one general “solar savings” number is an easy way to miss a deadline or count the same dollar twice.
- Identify the property. Record the address, state, city or county, electric utility, and service territory.
- Record property use and ownership. Note whether the home is owner occupied, a second home, rented, cooperative, a condominium, or used for mixed purposes.
- List every benefit separately. Include federal, state, local, utility, battery, storage, net metering, performance, and financing benefits.
- Write down each program’s terms. Record the administrator, current funding status, deadline, preapproval requirement, eligible equipment, income rule, maximum amount, and whether stacking is expressly allowed.
- Ask about cost treatment in writing. Confirm whether a rebate or subsidy reduces another benefit’s cost basis, goes to the homeowner or contractor, must be claimed before installation, or may be taxable under a particular tax regime.
- Confirm the current rules. Use DSIRE to find programs, then verify funding, service territory, deadlines, and stacking terms with the administering authority.
- Keep project records. Save contracts, itemized invoices, proof of payment, permits, completion records, equipment specifications, rebate approvals, utility correspondence, and tax forms.
- Document completion timing for older projects. For a project intended to qualify before 2026, retain evidence showing when original installation was completed, not only when a deposit was paid or a contract was signed.
Ask a tax professional to review unusual situations involving state incentives, utility payments, grants, transferable credits, community solar arrangements, business use, or financing structures. An installer can explain project details, but that does not replace confirmation from the program administrator or advice about tax treatment.
Common Misconceptions About Combining Solar Incentives
Misconception: Receiving a rebate automatically prevents a tax credit.
Correction: Some programs permit both benefits. The rebate may reduce the cost used to calculate the tax credit, though the answer depends on the specific programs and tax rules.
Misconception: Every incentive labeled a rebate reduces the federal tax credit basis.
Correction: Federal treatment depends on whether the payment is a public utility subsidy, a purchase price adjustment, or another type of benefit. A state program’s label is not decisive.
Misconception: Net metering is the same as an installation rebate.
Correction: Credits or payments for electricity sold to the grid generally did not reduce qualified expenses for the former §25D credit. That treatment was different from a qualifying public utility subsidy for purchasing or installing property.
Misconception: Paying before the federal deadline preserves the federal credit.
Correction: Under the IRS FAQ, installation completion generally determines when the expenditure is treated as made. A pre deadline payment did not preserve §25D eligibility for an installation completed afterward.
Frequently Asked Questions
Can a solar rebate and a tax credit apply to the same system?
Sometimes. Program rules may allow both, but the rebate can reduce the cost used to calculate the tax credit. The specific rebate, tax credit, and applicable tax treatment must be reviewed together.
Does a utility rebate reduce the amount eligible for a federal solar tax credit?
A public utility subsidy for purchasing or installing qualifying property generally reduced the qualified expense for the former §25D credit. A net metering credit for electricity sold to the grid generally did not.
Do state solar tax credits reduce the federal credit?
Not automatically. A state incentive may not be treated as a federal tax rebate or purchase price adjustment. Its federal and state tax treatment requires separate review.
Can a battery qualify for an incentive if it is installed without solar panels?
The answer depends on the particular program. The former federal rule covered qualifying battery storage technology, but it also imposed requirements such as a capacity threshold of at least 3 kWh. Current state, local, utility, and battery programs may use different rules.
Can homeowners combine solar incentives from a state, city, and utility?
Possibly, if each program allows it and the homeowner meets each program’s requirements. Confirm funding, deadlines, equipment rules, preapproval requirements, and stacking terms with every administering authority.
Does net metering count as a solar incentive or rebate?
It can be an economic benefit, but it is not necessarily an installation rebate or utility subsidy. For the former §25D rules, credits or payments for electricity sold to the grid generally did not reduce qualified installation expenses.
What documents prove that a solar installation met an incentive deadline?
Keep contracts, invoices, proof of payment, permits, completion records, equipment specifications, rebate approvals, and utility correspondence. For a pre 2026 §25D project, records showing when original installation was completed mattered more than a deposit or contract date alone.
Which solar incentives are still available for projects installed after 2025?
The supplied information does not establish a specific current incentive without the property location and program details. The former federal §25D credit is unavailable for qualifying expenditures made after December 31, 2025, but state, local, utility, and battery programs must be checked individually with their administering authorities.
Solar incentives can be combined in some cases, but the winning strategy is careful classification rather than optimistic arithmetic. Identify every program, verify its current rules, determine whether one benefit changes another benefit’s cost basis, and document the project timeline before relying on the combined savings.