The short answer depends first on when the property was installed. The federal Residential Clean Energy Credit generally equaled 30% of eligible costs for qualified solar and other clean energy property installed through December 31, 2025. Under the law and IRS guidance available as of September 30, 2026, a new residential solar or battery installation completed after that date generally does not qualify for the federal credit under Section 25D.
Paying a deposit, signing a contract, or paying the full invoice before the deadline does not automatically preserve eligibility. The project must also meet the rules for the taxpayer, the home, the equipment, and the costs being claimed. The credit is also nonrefundable, so it reduces federal income tax owed rather than automatically arriving as a cash payment.
To evaluate a project, work through four questions: Was the property installed during the eligible period? Does the taxpayer and home qualify? Which charges are actually eligible? Are the records complete enough to support the claim? The federal claim is generally made with the IRS Residential Clean Energy Credit guidance and Form 5695 for the year the property was installed.
Start With the Installation Date
The first date to verify is not necessarily the date on the contract, invoice, deposit, or loan paperwork. The credit is claimed for the tax year in which qualified property is installed or placed in service. In practical terms, you need a reliable record showing when the installation was completed or otherwise put into use under the applicable rules.
For the federal Residential Clean Energy Credit, qualified property generally had to be installed through December 31, 2025. A project paid for in 2025 but completed after that cutoff generally does not qualify merely because money changed hands before the deadline. A signed contract is not a time machine, and neither is a year end deposit.
This distinction matters especially for projects installed in 2026. Under the law and guidance reflected in the research for this article, a new residential solar or battery installation completed after December 31, 2025 generally does not receive the federal Section 25D credit. That conclusion concerns the installation date, not the year in which the tax return is filed.
For example, a return filed in 2026 may concern a qualifying project installed in 2025. Filing the return in 2026 does not turn a 2026 installation into a 2025 installation. Keep those two dates separate when reviewing the project.
Look for documentation that establishes the completion date. Useful records may include:
- A contractor completion certificate.
- Final inspection records.
- Utility interconnection approval or comparable utility records.
- Other records that clearly show when the qualified property was installed.
If the completion date is unclear, resolve that issue before calculating the credit. A neat invoice with the wrong date is still the wrong foundation for a tax claim.
Check Whether You, Your Home, and Your Equipment Qualify
The credit generally applies to qualified clean energy property installed at a home in the United States. The property and the person claiming the credit both matter. Owning the equipment alone does not answer every eligibility question.
A qualifying claimant may own or rent the main home in appropriate circumstances. A main home generally means the place where the taxpayer lives most of the time. A landlord who does not live at the property generally cannot claim the residential credit for improvements made to that rental property.
Eligible Section 25D categories can include:
- Qualified solar electric property.
- Qualified solar water heating property.
- Battery storage technology.
- Small wind property, geothermal heat pumps, and fuel cell property where the applicable requirements are met.
Battery storage can qualify even when it is not paired with newly installed solar, subject to the applicable rules and installation timing. IRS guidance identifies a minimum capacity of 3 kilowatt hours for battery storage technology. Keep the manufacturer information, model number, and capacity documentation with the rest of the project file.
Other equipment can have its own requirements. For example, solar water heating property may need to meet qualifying certification standards. Do not assume that a product qualifies simply because it is marketed as energy efficient or appears on a solar contractor’s proposal.
Shared ownership and unusual property arrangements deserve extra care. Joint occupants, fractional interests in condominiums or cooperatives, and taxpayers using more than one residence may be subject to allocation rules. One taxpayer should not automatically claim the entire project cost when ownership or use is shared.
Determine Which Project Costs Count
The full contractor invoice is not automatically an eligible cost. The useful number is the cost of qualified property and the labor that the rules allow, not simply the total amount charged for everything happening around the project.
Potentially qualifying costs can include qualified equipment and labor properly allocated to onsite preparation, assembly, and original installation. Required piping or wiring used to interconnect the property with the home may also qualify when it meets the applicable rules.
Costs that generally do not qualify include interest and loan origination fees. Unrelated improvements should also be separated from the clean energy property. Financing may make the project easier to pay for, but the financing charge does not become qualified equipment just because it appears on the same paperwork.
Roof work requires particularly careful allocation. Traditional roof trusses, shingles, and structural components generally do not qualify merely because they support solar panels. Solar shingles and solar roofing tiles are treated differently when they generate electricity and meet the applicable requirements.
Ask for an itemized contract and final invoice that separates the major categories. At a minimum, look for separate descriptions of:
- Panels, inverters, racking, and battery equipment.
- Labor for onsite preparation, assembly, original installation, and eligible interconnection work.
- Roofing or structural work.
- Permits and other separately listed charges.
- Financing charges.
- Rebates or other incentives.
That breakdown does not automatically decide every item. Permits, electrical charges, roof work, and other project costs may require proper allocation and verification. A single line labeled “solar project total” leaves too much work to do later.
Rebates and other incentives may also affect the federal cost basis or the federal tax treatment. Keep every rebate statement and ask how it should be reflected rather than quietly subtracting or including an amount without checking the applicable rules.
Understand the Credit Amount and Its Tax Limitation
For qualified property installed through December 31, 2025, the federal Residential Clean Energy Credit generally equaled 30% of eligible costs. That percentage applies to the costs that qualify, not necessarily to every charge on the contractor’s invoice.
The credit is nonrefundable. It can reduce federal income tax owed for the applicable year, but it cannot exceed the taxpayer’s federal income tax liability for that year. It is not automatically a 30% cash rebate, and calculating 30% of a project figure does not guarantee that amount will be paid as a refund.
Unused residential clean energy credit generally may be carried forward under the applicable rules. That means a taxpayer with insufficient federal tax liability may not use the entire calculated credit in the first year. Track the unused amount rather than treating it as lost or as an immediate cash payment.
This credit should not be blended with the separate Energy Efficient Home Improvement Credit. Different credits can have different rules, including different treatment of unused amounts. Use the instructions for the credit being claimed and reconcile the result with the taxpayer’s actual federal tax liability.
Prepare the Records and File Form 5695
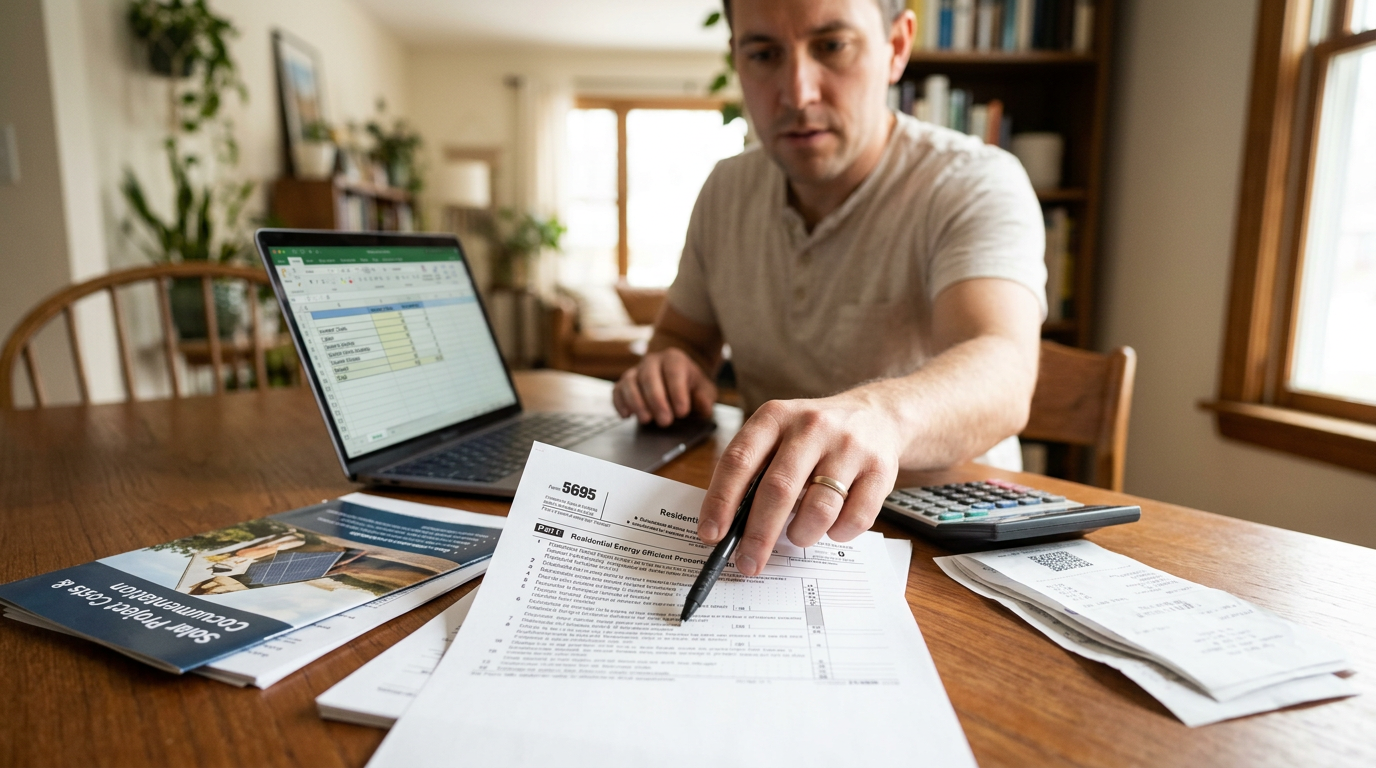
Taxpayers generally claim the Residential Clean Energy Credit on Form 5695, Residential Energy Credits, attached to the federal income tax return for the year the property was installed. The form is tied to the installation year, so confirm that date before choosing the tax year for the claim.
Receipts and installation records generally are not attached to the return. They should still be retained in case the IRS asks for support. They may also help establish the property’s adjusted basis if the home is sold later.
A practical project file should include:
- Signed contracts and change orders.
- Itemized invoices and receipts.
- Proof of payment.
- Contractor completion records.
- Permits and inspection records.
- Utility interconnection documents.
- Equipment specifications, model numbers, manufacturer materials, and warranties.
- Battery capacity information when claiming battery storage.
- Rebate and other incentive statements.
Before filing, compare the itemized project costs with the amount entered on Form 5695. Confirm that the claimed property was installed in the relevant year, remove financing charges and unrelated work, and apply any required allocation for shared ownership or multiple residences.
When the property arrangement or cost allocation is complicated, the Form 5695 calculation may require appropriate tax verification. That is especially true for shared ownership, condominiums, cooperatives, multiple residences, and projects combining several incentives.
Avoid the Most Common Solar Tax Credit Mistakes
Most problems come from treating a construction invoice as if it were a tax form. Before claiming the credit, check these common misunderstandings.
Misconception: Paying before the deadline automatically locks in the credit.
Correction: Installation timing matters. A deposit, contract, or payment made before December 31, 2025 does not necessarily preserve eligibility if installation is completed later.
Misconception: The credit is a guaranteed 30% cash rebate.
Correction: The credit is nonrefundable. It can reduce federal income tax owed, and unused credit generally may carry forward, but the calculated amount is not automatically paid as cash.
Misconception: Every cost on a solar invoice qualifies.
Correction: Qualified equipment and certain installation and interconnection labor may qualify. Interest, loan origination fees, unrelated improvements, and many traditional roofing or structural costs generally do not.
Misconception: Only property owners can claim the residential credit.
Correction: A renter may qualify for qualifying improvements to a rented main home in appropriate circumstances. A landlord who does not live at the property generally cannot claim the residential credit for that property.
Misconception: A battery must be installed with new solar panels.
Correction: Battery storage may qualify without newly installed solar when the applicable requirements are met. Verify the installation timing and the battery’s minimum capacity.
Misconception: Federal, state, utility, and local incentives are one combined program.
Correction: These are separate programs with different authorities, deadlines, eligibility rules, and possible tax consequences. Review each program on its own terms.
Check Other Incentives Separately
Federal eligibility does not answer every question about the total incentive package. State tax credits, utility rebates, grants, property tax exemptions, sales tax rules, and net metering benefits are separate from the federal Section 25D credit.
Those programs may have different application deadlines, equipment requirements, interconnection rules, and eligibility standards. Some may require an application before installation. Others may address rebates or the project’s tax treatment differently.
Check the current rules with the relevant state, local, utility, or tribal program administrator. Confirm whether a rebate reduces the federal cost basis, whether an application must be filed before work begins, and whether the equipment must meet a separate standard.
Without the taxpayer’s location and the current rules for the specific program, no universal conclusion can be made about those incentives. Treat local program information as a separate verification task, not as an automatic extension of the federal credit.
Frequently Asked Questions
Can I still claim the federal solar tax credit for a system installed in 2026?
Under the law and IRS guidance reflected in this article, a new residential solar or battery installation completed after December 31, 2025 generally does not qualify for the federal Residential Clean Energy Credit under Section 25D. The date the return is filed does not replace the installation date.
Does paying for solar before December 31, 2025 preserve eligibility if installation is delayed?
Not necessarily. Payment, a deposit, or a signed contract alone does not establish eligibility when the property is installed after the applicable cutoff. Keep records showing when installation was completed.
Do solar panels installed on a rental home qualify for the Residential Clean Energy Credit?
A renter may qualify for qualifying improvements to a rented main home in appropriate circumstances. A landlord who does not live at the property generally cannot claim the residential credit for that rental property.
Can I claim the credit for a battery installed without solar panels?
Battery storage may qualify even when it is not paired with newly installed solar, subject to the applicable rules and installation timing. IRS guidance identifies a minimum capacity of 3 kilowatt hours, so retain documentation showing the battery’s capacity.
Which labor, roof, permit, and electrical costs count toward the solar tax credit?
Qualified equipment and labor properly allocated to onsite preparation, assembly, original installation, and required interconnection piping or wiring may qualify. Interest, loan origination fees, unrelated work, and traditional roofing or structural components generally do not. Permits and other electrical charges need to be reviewed and allocated under the applicable rules rather than included automatically.
What documents should I keep for Form 5695 and an IRS audit?
Keep the signed contract, itemized invoices, receipts, proof of payment, completion records, permits, inspection records, utility interconnection documents, equipment specifications, battery capacity information when applicable, and rebate statements. These records generally are not filed with the return, but they may support the claim during an audit and help establish adjusted basis if the home is later sold.
What happens if the solar tax credit is larger than the federal tax I owe?
The credit is nonrefundable, so it cannot exceed the applicable federal income tax liability for the year. Unused residential clean energy credit generally may carry forward under the applicable rules. It should not be treated as an immediate cash refund.
How do utility rebates or state solar incentives affect the federal credit?
That depends on the specific incentive and its current rules. State, local, utility, and tribal programs are separate from the federal credit and may affect the federal cost basis or have their own application requirements. Verify the treatment with the relevant program administrator and, when needed, a tax professional.
To determine whether a solar or battery project qualifies, start with the installation date, then verify the home and equipment, separate eligible costs from financing and unrelated work, and preserve complete records. For property installed through December 31, 2025, the federal credit generally applied at 30% of eligible costs, subject to the nonrefundable tax limitation and any applicable carryforward. The cleanest claim is built from an itemized invoice and reliable installation records, not from the largest number on the proposal.